

MAJORITY: Mobile banking

- 12.00K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on MAJORITY: Mobile banking from Appgk
I approached MAJORITY as a practical finance app rather than as a replacement for every banking service. Its main appeal is straightforward: it brings a US account and debit card into one mobile experience, with a focus on people who need to manage money in the United States, send money home, and work toward building credit. I found that combination more useful than a generic banking pitch because it speaks to a particular situation: someone settling into the US, supporting family abroad, or trying to organize everyday spending without beginning with a traditional bank branch.
The app is free to download, and its Everyone age rating makes it approachable for a broad audience. It was developed by MAJORITY USA, LLC and has grown into a widely used finance app, with more than a million installs and a 4.7 average from roughly twenty-three thousand ratings. Those numbers do not decide whether it is right for you, but they do suggest that it has reached well beyond a small niche.
What I would check before choosing a mobile banking app
My first decision criterion is not the number of features. It is whether the app matches the way I actually move money. A person who only wants a conventional checking account may judge MAJORITY differently from someone who needs a US account while building a new life in the country. The app’s emphasis on a US account, debit card, international support, and credit-building tools gives it a distinct purpose, so I would begin by asking which of those needs matters most.
The second question is how much of my financial routine I want inside a phone. Mobile banking is convenient when I want to check a balance, use a card, or handle a transfer without visiting a branch. At the same time, a phone-first service requires me to be comfortable with digital account management. If I prefer face-to-face help, paper statements, or a large branch network, a traditional bank may feel more reassuring even if it takes more effort.
Best Parts of MAJORITY: Mobile banking
Things to Keep in Mind About MAJORITY: Mobile banking
I would also separate the idea of a debit card from the idea of credit. A debit card spends money already connected to the account, while credit-building is a longer-term goal. MAJORITY brings those ideas together in one service, but I would not treat access to the app as an instant improvement to a credit profile. Anyone choosing it for that reason should read the in-app terms carefully, follow the available guidance, and keep expectations realistic.
Another useful test is the international part of my routine. Sending money home can be more important than small interface details, especially when family support is a regular responsibility. I would want to know exactly how a transfer works before relying on it for an urgent payment: which recipient details are needed, how I review the amount, and when the recipient can use the money. The app’s focus makes this workflow central, but responsible users should still verify every transfer before confirming it.
News and Features Related to MAJORITY: Mobile banking

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic everyday use case
Imagine I have recently moved to the US and need a simple way to receive money, pay for groceries, use a debit card, and send part of my income to family. With a standard banking option, I might need to compare a checking account, a separate remittance service, and another tool for credit education. MAJORITY is appealing because it aims to bring those needs into one account experience.
In that situation, I would set up the account first, make sure my personal details are correct, and use the debit card for predictable daily purchases rather than treating it as a reason to spend more. Before sending money home, I would create a repeatable routine: check the available balance, confirm the recipient, review the transfer amount, and save the confirmation. That small habit matters because combining everyday spending with family transfers can make an account harder to track if I do everything impulsively.
Don't want to read the full review?
The app’s promise of a US account without an SSN is especially relevant to people who are navigating the US financial system and do not have that document available. I would still approach account opening carefully and provide whatever information the app requests during enrollment. The practical value is not that every situation becomes effortless; it is that the service is designed around a group often poorly served by conventional onboarding.
Where the app is strongest
For me, the strongest part is the way MAJORITY connects several needs that are often split across different services. A US account and debit card cover ordinary spending, while the ability to send money home addresses an international household need. The credit-building angle adds a longer-term purpose. That combination makes the app more focused than a broad banking product that tries to serve everyone equally.
Screenshots
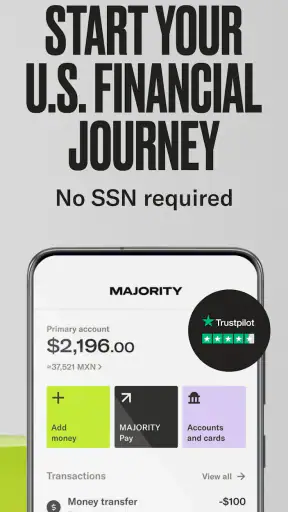
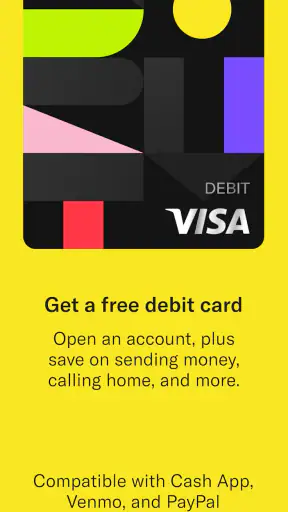
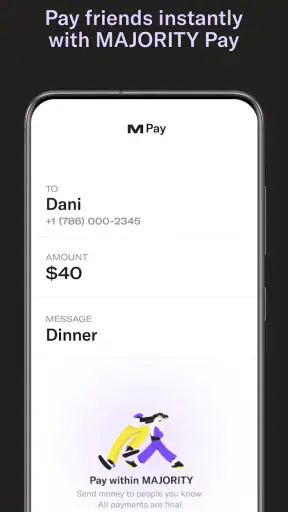
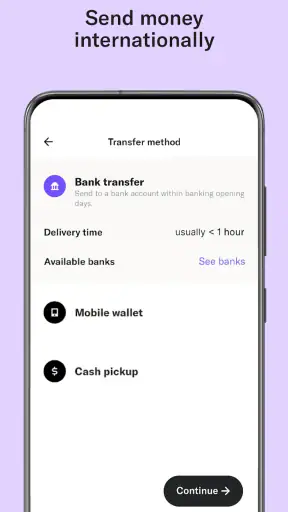
The debit card can also make budgeting more tangible. I find it easier to think about a weekly spending limit when purchases come directly from the account balance. A useful workflow would be to separate essential spending from money intended for family transfers, then check the balance before using the card. This is not a sophisticated budgeting system, but it can prevent the common mistake of treating money reserved for another person as available spending money.
Another non-obvious advantage is reduced account sprawl. Every additional financial app creates another password, notification stream, balance to monitor, and place where a transfer can go wrong. Keeping the US account, card activity, and money-home workflow close together may be worth more than having a long list of specialized tools. I would particularly value that if I were managing finances across borders and wanted fewer moving parts.
The app is also a sensible starting point for someone who feels excluded by the usual banking path. Its stated focus on access without an SSN gives it a clear audience rather than making it merely a smaller version of a conventional bank. That does not mean the experience will suit every applicant, but it does mean the product is solving a more specific problem than “banking on your phone.”
Small habits that make the service easier to manage
I would use the account with a simple three-bucket mental model: money for immediate spending, money reserved for transfers, and money left untouched for upcoming obligations. Even if the app does not replace a full budgeting platform, this approach makes the debit card safer to use. It also helps me notice whether a transfer home is affordable before I commit to it.
I would review card activity after important purchases instead of waiting until the end of the month. This is particularly useful when several family members or household expenses depend on the same balance. A quick review can catch a mistaken amount or an unfamiliar transaction while the details are still fresh.
Finally, I would treat credit-building as a process to monitor, not a button to press. I would read the relevant explanations inside the app, understand what actions are expected, and avoid changing my routine based on assumptions. That distinction is easy to miss in a product that combines banking and credit language, but it is one of the most important practical lessons for a new user.
Where another type of service may fit better
MAJORITY is not automatically the best choice for someone who already has a full-service US bank and only needs occasional international transfers. In that case, a familiar bank may offer a broader set of everyday services, while a dedicated transfer provider may be easier to compare for one specific transaction. I would not switch simply because one app combines several functions if my current arrangement is already reliable and inexpensive for my needs.
It may also be a weaker fit for people who want advanced financial tools. A traditional bank or a more established personal-finance platform may be preferable if I need extensive account types, detailed spending analysis, investment services, or a large support infrastructure. Those are different priorities from MAJORITY’s focused experience, and choosing the narrower tool would not make sense if I expect it to behave like a complete financial institution for every possible task.
People who strongly prefer cash-based banking should think carefully as well. A mobile account and debit card are most useful when I can comfortably manage balances and transactions digitally. If my routine depends on frequent branch visits or personal assistance, the convenience of a phone app may not compensate for the change in habits.
There is also a trade-off in putting several important activities together. One app can simplify life, but it can also make that app more central to my financial routine. I would keep records of important transfers, protect access to the phone and account, and avoid assuming that convenience eliminates the need for basic financial organization. The more responsibilities I place in one service, the more carefully I should monitor it.
For international transfers, I would compare the complete transaction experience rather than judging the app by the headline feature alone. The relevant questions are whether the recipient details are easy to enter, whether the confirmation screen is clear, how often I send money, and whether I need a service designed only for remittances. Someone who sends money home every week may value the integrated account; someone who sends money once in a while may prefer a separate tool that is easier to use for that single purpose.
What switching really involves
Moving to a new financial app is not just a download. I would need to update the places where my debit card is used, remember which income or payments connect to the account, and explain the new transfer routine to anyone receiving money from me. Even when the new service looks simpler, the transition can create confusion if I close or abandon an old account too quickly.
My advice would be to start gradually. I would install the app, complete the account setup, understand the card and transfer screens, and test my personal workflow before making it the center of my finances. I would keep enough money available for essential expenses elsewhere during the changeover. This is not a criticism of MAJORITY specifically; it is a sensible safeguard whenever a mobile service becomes responsible for important payments.
I would also check the current in-app information before making decisions about fees, limits, eligibility, card use, or credit-building steps. Financial products can change, and a review cannot replace the terms shown at the moment I open an account. The free price makes trying the app easier, but “free to download” should not be confused with a promise that every possible transaction or service will always have no cost.
The current version is 5.14.0, and the app supports devices running Android 9 or later. That is useful to know before installing, especially if I use an older phone. I would update the operating system where possible and keep the app current, since finance apps handle information that deserves a well-maintained device and careful account security.
Who should use it, and who should skip it?
I would recommend MAJORITY to a newcomer to the US who wants a mobile-first account and debit card, particularly if sending money home is part of regular household planning. It also makes sense for someone interested in exploring credit-building guidance while keeping everyday spending in one place. The app’s value is strongest when those needs overlap.
I would be more cautious about recommending it to a person who only wants a basic account with no international activity and already has a dependable bank. That user may gain little from switching. I would also point people with complex financial needs toward a broader banking setup, because a focused app should not be expected to replace every account, service, and support channel.
Families should think about control and responsibility before sharing access or relying on one card for several people. I would keep the account holder’s login private, establish a clear plan for transfers, and avoid handing over account access as a substitute for sending money through the intended process. That is a practical boundary that can prevent misunderstandings.
My recommendation after using it as a decision guide
My overall view is positive, but specific. MAJORITY is most convincing as a focused finance app for people who need a US account and debit card while also staying connected to family abroad. Its free entry point, mobile format, and attention to users who may not have an SSN make it easier to consider than a conventional banking route that was not designed around those circumstances.
I would choose it when the integrated experience solves a real problem in my daily life. I would not choose it merely because it has a high rating or because putting everything in one app sounds convenient. The rating, from around twelve thousand written reviews as part of its broader user feedback, is encouraging, but my own needs would still matter more than popularity.
The best reason to try MAJORITY is the combination of US banking access, a debit card, money transfers home, and credit-building in one focused service. Before relying on it fully, I would read the current account details, understand the transfer process, plan the switch carefully, and keep my spending organized. If that matches your situation, I think it is worth exploring. If you want a branch-centered bank, advanced financial products, or only an occasional remittance tool, another category may serve you better.
In short, I see MAJORITY as a practical bridge rather than a universal banking answer. It is designed for a particular kind of financial life, and that focus is its main strength. For the right user, it can reduce the number of separate tools needed to manage US spending and support family abroad. For everyone else, the smarter choice may be to keep a broader traditional account or select a specialist service that does one job exceptionally well.
MAJORITY: Mobile banking FAQ
What is MAJORITY, and who is the mobile banking service designed for?
MAJORITY is a mobile banking service created primarily for immigrants, international families, and people who regularly send money across borders. After signing up through the app, users can access banking features, money transfers, international calling options, and other services in one place. Availability, eligibility, and specific benefits may depend on your country of residence and the details of the current membership plan.
Do I need identification or a Social Security number to open a MAJORITY account?
Yes, MAJORITY generally requires users to complete an identity-verification process before receiving full access to its banking features. Depending on your location and eligibility, the app may request personal information, a government-issued identification document, and other details required by financial regulations. The exact requirements can vary, so users should review the application instructions carefully before downloading and beginning registration.
Can I use MAJORITY to send money internationally?
International money transfers are one of MAJORITY’s main attractions, especially for users supporting relatives abroad. The app may allow transfers to selected countries and delivery methods, but supported destinations, fees, exchange rates, limits, and processing times can change. Before confirming a transaction, check the final cost and recipient details in the app, since transfers may not always be reversible.
Does MAJORITY charge a monthly fee or other transaction fees?
MAJORITY typically operates through a membership model, meaning users may need to pay a recurring fee to access its complete set of services. Additional charges can apply to certain transactions, card-related services, ATM usage, currency conversion, or international transfers. Pricing and promotional offers may change, so review the current fee schedule and subscription terms before completing registration.
Is MAJORITY a traditional bank, and is my money protected?
MAJORITY provides mobile banking services, but it is important to understand that the app itself may not be a traditional bank. Banking services and payment accounts can be provided through regulated partner institutions, depending on the product and your location. Read the account agreement to learn who holds your funds, what protections apply, and how customer support handles disputes, unauthorized activity, or account restrictions.











